Rakesh (name changed), a project engineer in Dubai, sent me a screenshot last February. His bank had suggested he “save tax” by opening a PPF account for his daughter and putting Rs 1.5 lakh into an NSC.
He wanted to know which one to pick.
The honest answer was neither. As an NRI he cannot open either. What made it worse was that he had been filing under the new regime for two years, where most of those deductions would not have counted anyway. He was shopping for a lock that did not fit his door.
⚡ Quick Answer
NRIs still get 80C, 80D, 24(b) home loan interest, 80E, 80G and 80TTA, but only under the old regime. The new regime is the default and strips almost all of them. You cannot open PPF, NSC, SCSS or Post Office schemes. Your biggest genuine savings are usually NRE and FCNR interest (fully exempt), Section 54 and 54EC on property gains, and a DTAA treaty claim.
Must Read – NRI Tax in India on Indian Income for FY 2026-27
First, Pick the Right Regime
Everything else follows from this one choice. Since the new regime became the default, it applies unless you actively opt out when filing.
Think of it like two mobile plans. The new regime is the cheaper base tariff with no add-ons. The old regime costs more per unit but lets you claim back a lot. If you have a home loan, health insurance premiums and ELSS running, the old regime often still wins for an NRI. If your only Indian income is NRO interest, the new regime is simpler and usually cheaper.
Run both numbers before you file. Not before you invest. That order matters.
Income That Is Simply Not Taxed
- Interest on NRE savings and NRE deposits, while you are a non-resident.
- Interest on FCNR(B) deposits, also while non-resident.
- Interest on notified savings certificates and specified bonds issued to non-residents.
- Long-term capital gains up to Rs 1.25 lakh a year from listed shares and equity mutual funds. Above that the rate is 12.5%. The old Rs 1 lakh threshold and 10% rate no longer apply.
Note what is missing from that list. NRO interest is fully taxable, with TDS at 30% plus surcharge and cess.
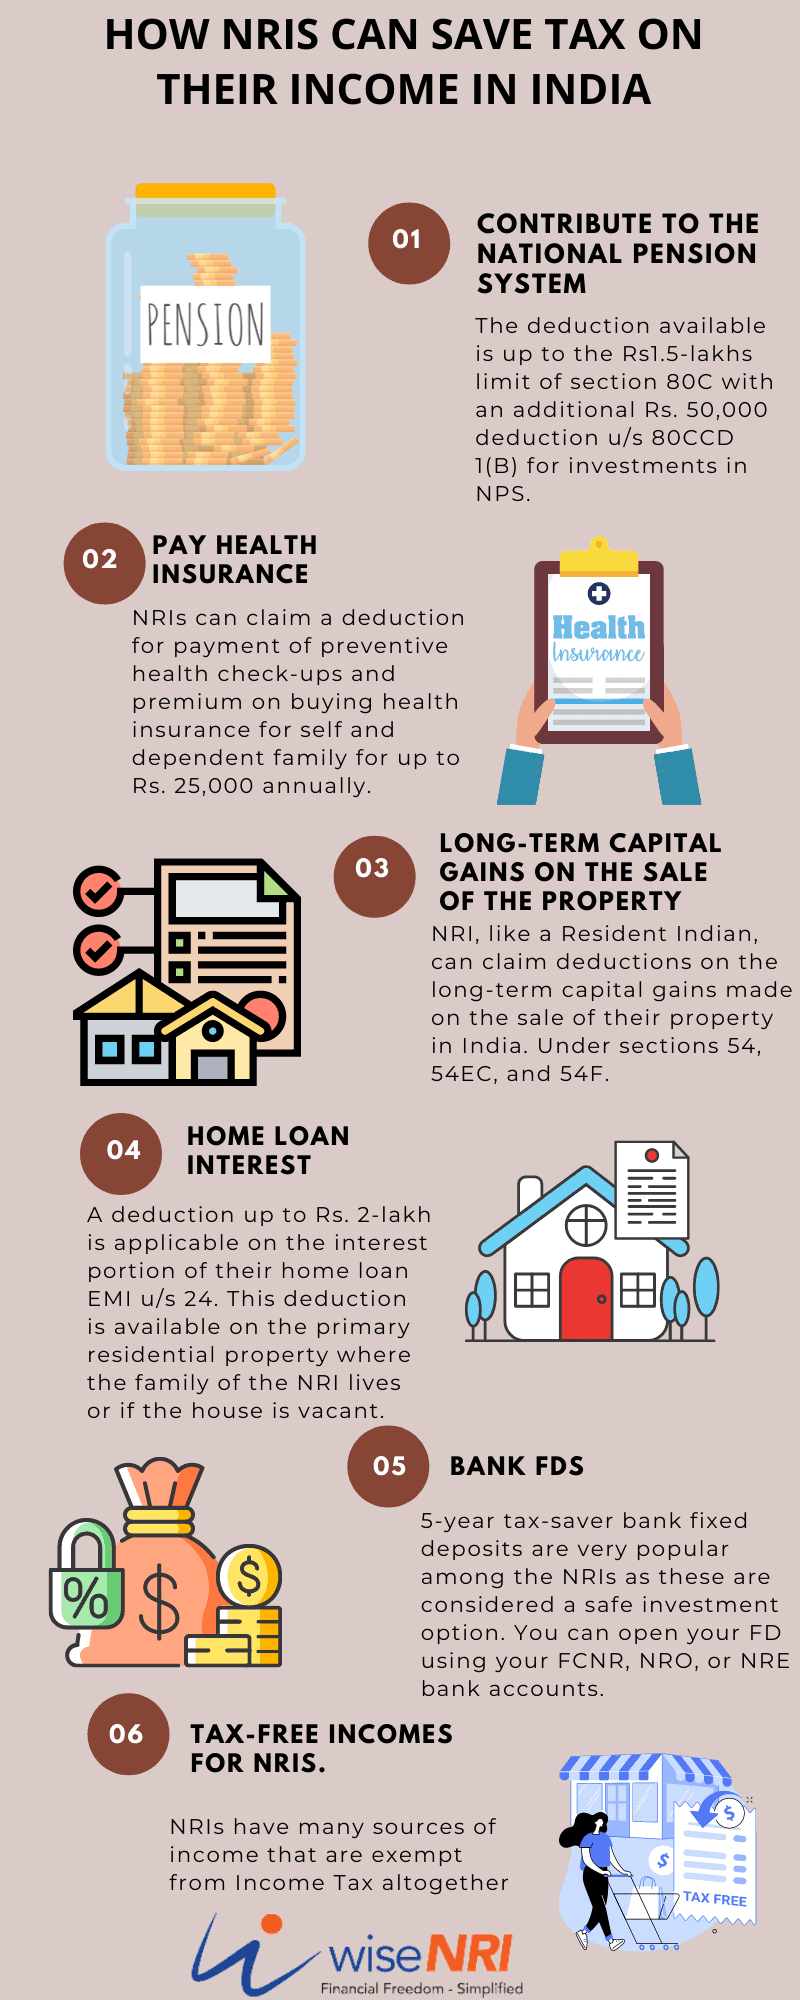
Section 80C: What an NRI Can and Cannot Use
| Instrument | Available to NRIs? |
|---|---|
| ELSS mutual funds | Yes, 3-year lock-in |
| Life insurance premium (any category) | Yes |
| Children’s tuition fees, Indian institutions | Yes, up to two children |
| Home loan principal, stamp duty, registration | Yes |
| ULIPs | Yes |
| PPF | No new account |
| NSC, SCSS, Post Office deposits | No |
| 5-year tax-saver bank FD | Yes, through NRO |
The overall 80C cap remains Rs 1.5 lakh and applies only under the old regime.
On PPF specifically. An account you opened while resident runs to maturity. It cannot be extended in the usual five-year blocks once your status changes. Confirm the current position with your bank before making any fresh deposit, because branches apply this inconsistently.
Your Property Is Usually the Biggest Lever
Interest on a home loan gets you up to Rs 2 lakh a year on a self-occupied or vacant house under Section 24(b). If the property is let out, the full interest is deductible against rental income, though set-off against other heads is capped at Rs 2 lakh a year.
On rent, the flat 30% standard deduction and municipal taxes paid come off before tax. Many NRI landlords forget the municipal tax receipt entirely.
Sections 80EE and 80EEA are closed. Those extra first-home benefits applied to loans sanctioned within specific windows that ended on 31 March 2022. If an old article told you otherwise, it was written before the window shut.
Also read – Rental Income Rules for NRI Landlords
Selling Property: Sections 54, 54EC and 54F
- Section 54: reinvest long-term gains from a residential house into one Indian residential house, bought one year before or two years after the sale, or built within three years. The exemption is capped at Rs 10 crore of investment.
- Section 54EC: put up to Rs 50 lakh of the gain into bonds of REC, PFC or IRFC within six months. Lock-in is five years, not three. NHAI stopped issuing these bonds.
- Section 54F: for gains on assets other than a house, where the whole net sale value goes into one residential house.
Long-term gains on property are now taxed at 12.5% without indexation for non-residents. That single change makes reinvestment planning far more valuable than it used to be.
Health, Education and Giving
Section 80D allows up to Rs 25,000 for health insurance covering you, spouse and children, and another Rs 50,000 for senior citizen parents. Preventive health check-up costs sit inside those limits up to Rs 5,000. They are not an extra amount on top, which is a very common mistake.
Section 80E gives unlimited deduction on interest paid on an education loan taken from an Indian lender, for eight years. Section 80G covers donations to approved Indian charities, with a valid receipt and the institution’s registration number.
The Two Treaty Tools Most NRIs Never Use
A Tax Residency Certificate from your country of residence, plus Form 10F, can bring your Indian TDS down to the DTAA rate instead of the domestic 30%. On NRO interest that can mean 10% or 15% instead of 30%, depending on the treaty.
Second, Section 89A with Form 10-EE lets you defer Indian tax on income accruing in a foreign retirement account in a notified country until you actually withdraw. The US, UK and Canada are notified. For anyone with a 401(k) or an ISA-style pension pot, this is worth a conversation with your CA.
Where the real money hides
Rakesh had Rs 1.5 lakh he wanted to “save tax” with. Under the old regime that Rs 1.5 lakh of 80C would have saved him about Rs 45,000 at the 30% slab. Meanwhile he had Rs 62 lakh sitting in an NRO fixed deposit instead of NRE, paying nearly Rs 1.5 lakh of avoidable tax on the interest every single year. He had also never filed Form 10F, so TDS on that interest ran at 31.2% rather than the 12.5% his treaty allowed.
In twenty-five years I have rarely seen an NRI lose money on the deduction they missed. They lose it on the account they never moved.
Mental Accounting and the March Rush
There is a behavioural habit called mental accounting: we file money into separate mental boxes and treat each box by different rules, even though rupees are identical.
Tax saving gets its own box, opened every February. Money goes into it in a hurry, usually into a policy with a 15-year commitment that gets abandoned by year four. Meanwhile the much larger box marked “my NRO deposit” is never opened at all, because it does not feel like a tax decision.
The Rs 1.5 lakh you rush is visible. The Rs 60 lakh you ignore is not. Ek baar poora hisaab dekh lijiye, phir decide kijiye.
Buying a policy every February and still paying too much tax?
The fix is usually structural, not another product.
Questions NRIs Ask Me Every Year
Can I claim 80C if I file under the new regime?
No. You have to opt out of the new regime at the time of filing to claim it.
Can I open a PPF account for my child in India?
Not while you are an NRI. Neither for yourself nor as guardian.
Is NPS still open to NRIs?
Yes. An NRI aged 18 to 70 with an NRE or NRO account can invest, and the extra Rs 50,000 under 80CCD(1B) is available under the old regime. Contributions must come from Indian rupee accounts.
Do I get the Section 87A rebate?
No. That rebate is for residents only, in both regimes.
Can I use the basic exemption limit against capital gains?
No. Residents can shelter gains under any unused exemption limit. Non-residents cannot. Mutual fund taxation details are here.
What if I am returning to India soon?
Then the biggest tax saving available to you is RNOR status, which can shelter your foreign income for two to three years. Read how RNOR works before you book the flight.
Rakesh moved his deposit, filed one form, and saved more in a single afternoon than eight years of February purchases had ever given him.
The best tax saving usually looks like paperwork, not a product.
💬 Your Turn
What is the last product someone sold you as an NRI tax saver, and did it actually reduce your tax bill? I read every comment.


I am an NRI I would like to purchase property at Mumbai which is more than 50 lakhs. How much Tds I have to deduct and pay them remaining amount
Hey Shankar,
As an NRI purchasing property in Mumbai over 50 lakhs, you’re required to deduct TDS (Tax Deducted at Source) at 20% of the property’s value. You need to pay the remaining amount after deducting this TDS to the seller. Ensure compliance with Indian tax regulations and consider consulting with a tax advisor for precise guidance on TDS deductions and property purchase transactions for NRIs.
Sir, is the TDS for nri on sale consideration or on capital gains on the sale of long term residential property?
Hello Namrata,
The TDS (Tax Deducted at Source) for NRIs (Non-Resident Indians) is applicable on the sale consideration of long-term residential property, not on the capital gains.
I have a flat and want to sell it.Will you provide all taxation services?
Hi Ramesh,
Please consult with CA.
I am an NRI with 4 years of employment abroad and planning to return to India in September. I have NRI savings that I want to remit to India before I return back to India. The NRI savings are already taxed in the foreign country. For the current Fiscal year in the foreign country (Jan to Dec 2022) I am a tax resident in the country. But as I return in September to India I am also a tax resident in India. Can I get DTAA benefit for the current year? Is my previous years NRI savings taxable if I remit now to India?
Hi Aravind,
Yes. You can get the DTAA benefit
HiI gave loan of 16 lacs to some one in india i am USA greencard holder how i can i bring this money to usa without paying tax in india or usa will this amount comes is taxable or should i split payment can i deposit this amount in NRO account in india please advise thanks
Hi Sanjeev,
The repayment of the principal amount and the interest can be done only to the NRO account of the NRI
I am NRI and staying in Qatar since 2015. I had a Insurance policy with LIC and private insurance company both purchased in year 2018. Both are traditional insurance policies. Private insurance company refund GST on premium while LIC denied to refund GST. So my question is what is the rule for GST on traditional insurance policy for NRI. Can I liable to pay GST or not? Pl clarify.
Hi Chirag,
Please consult with your CA regarding this.
I am OCI card holder Non-Indian having NRI/FCNR deposits. I overstayed in India from 20/02/2020 till date. I was NRI since over 15 years. Please advise if the above deposits are taxable as the interest income exceeds 15lakh. Do I file the return? I have never filed the return.
Checking your article on ‘How NRIs can save on their income in India’ , do you have more information on saving interest on notified bonds and savings certificates issued by Govt. of India?
I haven’t converted my savings bank account to NRO account since long time as I am a citizen of another country with PIO status.
Q1. I am an NRI staying in the US. Do I owe tax to the US govt on interest earned on my PPF account in India, even though I am continuing the PPF account and not withdrawing anything?
Q2. Do you have any pros/cons of winding up all accounts in India and repatriating all money to the US?
I am in Denmark, I have NRE and NRO account in India. I am getting some interest on my NRO account and I am paying tax as per the slabs. the question is Do I need to pay the tax for interest earned on an NRO account in Denmark?
If I sell a property at purchase price do l still pay tax and will it be difficult to repatriate money?
Could you please publish an article on guidance for educating NRI investors on the taxation please based on deemed residence status when india income crosses 15 L.This is very important as gain from overseas funds are added to income. I have sizable stake.
I am NRI…I have cumulative interest NCDs bought in secondary…if I hold till maturity what is the tax implication.
Very useful and educative.
Thanks 🙂