Priya, an NRI in the US, assumed her Indian rental income tax would simply offset against her US liability without any extra paperwork. It doesn’t work automatically. She needed a Tax Residency Certificate, a specific form filed with Indian tax authorities, and documentation on the US side, before that credit actually applied. (name changed)
⚡ Quick Answer
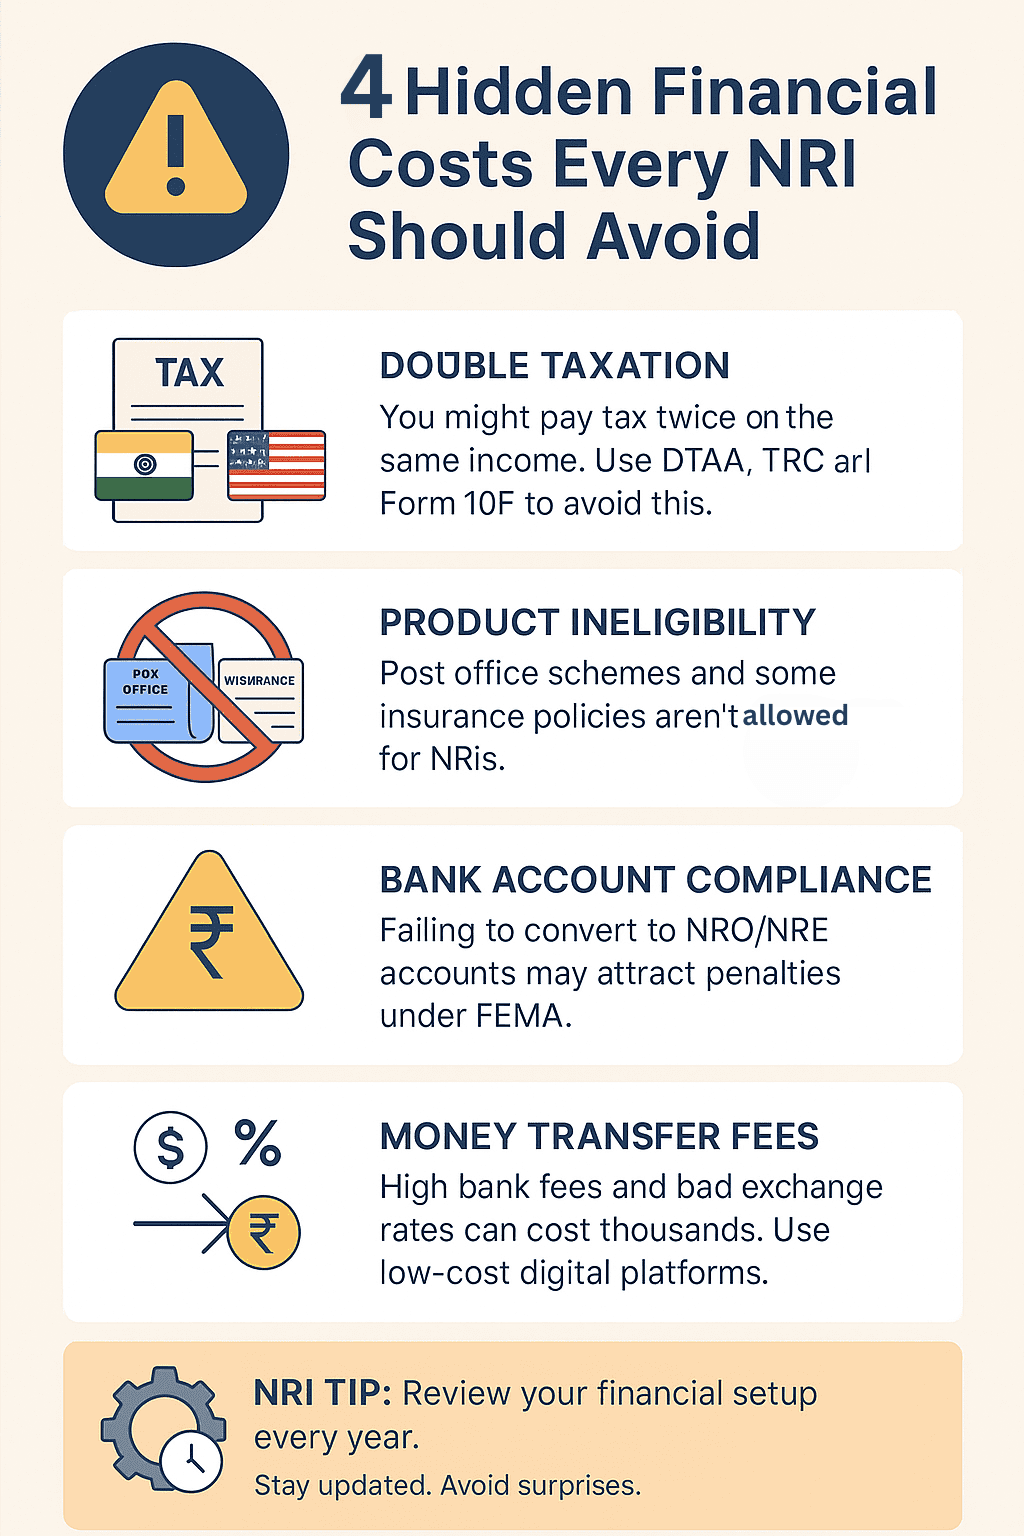
The most common hidden costs for NRIs are paying more tax than necessary due to unclaimed DTAA credits, holding investment products they’re no longer eligible for, FEMA penalties for not converting a resident bank account to NRO, and money transfer fees eaten up by wire charges and unfavorable exchange rates. Each is avoidable with basic paperwork and awareness, but each one quietly costs real money when ignored.
You’re living the NRI life, earning in a strong foreign currency, building a life abroad. But are you unknowingly leaving money on the table? The benefits of being an NRI get plenty of airtime. The hidden financial costs that can quietly erode your wealth deserve equal attention.
Must Check: Five Financial Tips for NRI Small Business Owners
Double Taxation: Are You Paying More Than You Should?
If you’re paying tax on Indian income, rental income, dividends, or interest, and also filing taxes in your country of residence, you may be leaving a legitimate tax credit unclaimed under the DTAA between India and your resident country. Depending on the country, you may also be able to deduct expenses like loan interest against rental income, or carry forward a rental loss to offset future income, benefits that only apply if you actually claim them correctly.
To avoid overpaying, check whether a DTAA exists between India and your country of residence, and get a Tax Residency Certificate (TRC) from your resident country. Submit Form 10F to Indian tax authorities to establish DTAA eligibility, along with any self-declarations and supporting documents your bank needs for reduced TDS rates. If you’re claiming the equivalent relief abroad, check that country’s specific documentation requirements too.
Product Eligibility: Are You Investing in the Wrong Places?
Not every investment avenue open to you as a resident Indian stays open once your status changes to NRI. Holding products designed for residents can trigger penalties for non-compliance with FEMA or RBI guidelines.
Before investing in anything in India, verify NRI eligibility directly, and always ask for product documentation from whoever’s selling it, a bank relationship manager, agent, or advisor. NRIs are typically restricted from Post Office Savings Schemes and new Sukanya Samriddhi Yojana accounts for daughters, for instance, and some insurance policies are designed for residents only. If you invested in something as a resident and later became an NRI, it’s your responsibility to inform the relevant institution and restructure accordingly.
Must Read: NRI Checklist
Bank Account Residency Rules: Avoid These Penalties
FEMA regulations require NRIs to close or convert resident savings and current accounts to NRO accounts. Non-compliance carries real penalties:
- A fine of up to three times the amount held in the account
- A flat fine of ₹2,00,000 if the amount isn’t easily quantifiable
- An additional ₹5,000 per day from the first day of non-compliance until the fine is paid
The Penalty Clock Doesn’t Wait for You to Notice
The ₹5,000 daily penalty starts from the first day your resident account should have been converted, not from the day you get caught. Someone who’s been abroad for two years without converting could already owe a penalty running into lakhs, entirely unknowingly. This is worth checking today, not the next time you happen to think about it.
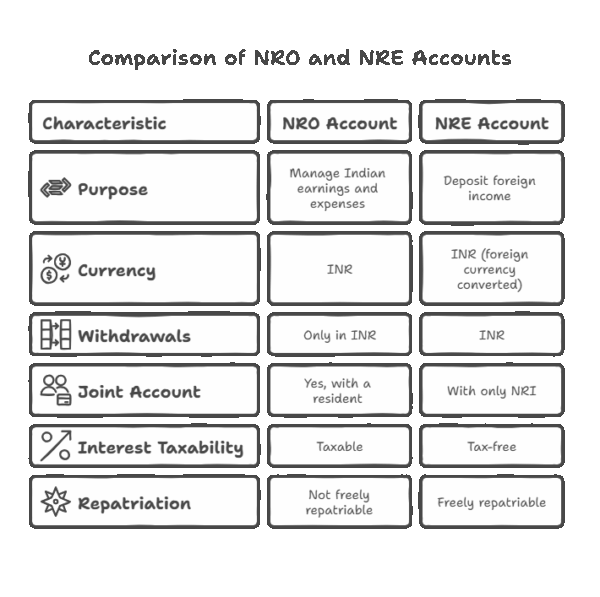
An NRO account manages earnings and expenses in India, with withdrawals possible only in INR, and can be opened jointly with a resident, useful if family needs access during a medical emergency without you having to send money from abroad. An NRE account, by contrast, holds foreign currency deposits converted to INR, comes with an international debit card for round the clock transactions, and both the interest earned and the balance itself are freely repatriable and tax free.
Money Transfers: The Hidden Charges NRIs Forget
When Rishabh, an NRI in the Netherlands, needed to urgently send money to his parents in India for a medical emergency, he learned firsthand that international transfers are neither straightforward nor cheap. He didn’t have enough in his NRO account, so he had to transfer from abroad, and it cost him both money and time he didn’t have to spare. (name changed)
Traditional banking channels, telegraphic transfers and foreign currency demand drafts, can take up to 72 hours to process. Wire transfer fees typically run USD 20 to USD 75 per transaction, before service charges, GST, and other costs stack on top.
Must Check: How Can NRIs Manage Debt?
Then there’s the exchange rate itself. Banks don’t always offer the market rate. If the market rate is ₹96 per Euro but your bank offers ₹95, that one-rupee gap costs ₹5,000 on a €5,000 transfer alone. Small, avoidable, and easy to miss if you’re not comparing rates.
To avoid these losses: keep some funds in an NRO account that family can access directly, compare services and exchange rates before transferring, avoid frequent small transfers that each carry their own fee, and negotiate with your bank for better rates on larger transfers. Digital transfer platforms have become genuinely competitive on both transparency and rates, worth comparing against traditional bank transfers, ideally with a small test transfer before you need to rely on one urgently.
Instant UPI transfers linked to international mobile numbers are available in some countries and banks, though coverage is still limited. Check with your specific bank and country, and if it’s available, set it up and test it in advance so it’s ready when an emergency actually hits.
Frequently Asked Questions
How do I know if my DTAA credit was actually applied correctly?
Check your Indian tax return and your resident-country return together; if the same income appears fully taxed in both without a credit reducing one side, the DTAA claim likely wasn’t processed. A CA familiar with cross-border filing can confirm this quickly.
What happens if I’ve been holding a resident account as an NRI without realizing it?
Convert or close it as soon as you notice. The penalty clock runs from the date of non-compliance, so acting now limits further exposure even if some penalty risk already exists.
Are digital money transfer platforms actually cheaper than banks?
Often yes, on both fees and exchange rate transparency, but compare the all-in cost (fee plus exchange rate spread) rather than just the headline fee, since some platforms recover margin through the rate instead.
As an NRI, your focus is naturally on building a life abroad. Managing your financial ties in India wisely deserves equal attention. Hidden costs, regulatory oversights, and outdated financial products can quietly chip away at your wealth. Stay informed, review your financial setup regularly, and don’t hesitate to get professional advice when something feels unclear.
None of these costs announce themselves. They just quietly show up in what you don’t have left.
Not sure which of these apply to you?
Let’s do a quick check on your accounts, investments, and DTAA claims.
💬 Your Turn
Have you run into a hidden cost we haven’t covered here? Add it in the comments, it might help someone else avoid the same mistake.